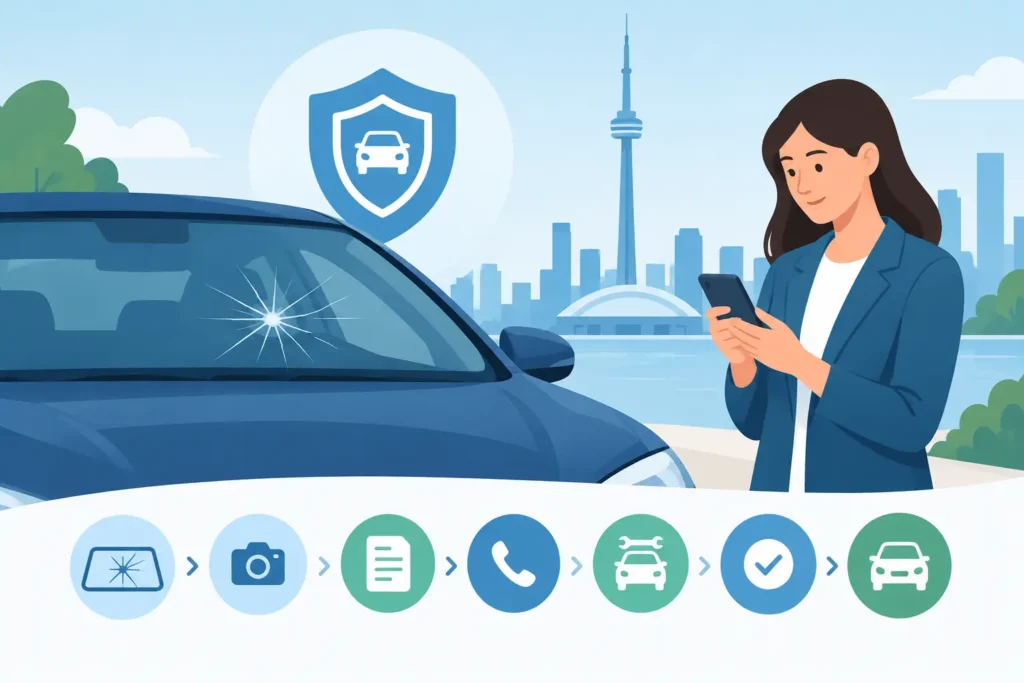
A rock strike on the 401 can turn into a spreading crack before the drive home. If you are searching for a windshield insurance claim Ontario drivers can handle without unnecessary delays, the first priority is simple: protect your visibility, document the damage, and get a qualified assessment before the problem grows.
Windshield claims are often straightforward, but coverage, deductibles, claim reporting, and calibration requirements vary by policy and vehicle. A fast repair may be the right answer for a small chip. A replacement may be necessary when damage affects the driver’s view, reaches an edge, or compromises the glass’s strength. Knowing the difference helps you make a safe decision without guessing.
1. Determine whether the windshield is safe to drive with
Do not judge a damaged windshield by appearance alone. A small chip may be repairable, while a crack can spread quickly with road vibration, temperature changes, defroster heat, and potholes. Damage near the windshield edge is especially concerning because it can weaken the glass and affect the windshield’s role in supporting the vehicle roof during a collision.
Avoid driving when a crack blocks or distracts from your line of sight, the glass is shattered, or visibility is reduced by loose fragments. If you need help at home, work, or roadside in Toronto, Scarborough, or the GTA, mobile auto-glass service can prevent an unsafe drive to a shop.
2. Check your policy before opening the claim
In Ontario, windshield damage caused by stones, debris, vandalism, falling objects, or weather is commonly handled under comprehensive coverage. If the damage happened during a collision, different coverage may apply. The details of your policy matter more than a general rule.
Look for your comprehensive deductible, sometimes listed under specified perils or all perils coverage depending on the policy. Your deductible is the amount you pay before insurance contributes to an approved repair or replacement. Some insurers may handle a repair differently from a full replacement, but do not assume a deductible is waived. Confirm it directly with your insurer or broker.
It is also reasonable to ask how the claim may be recorded and whether it could affect future premiums. The answer depends on your insurer, policy history, coverage type, and circumstances of the loss. A reputable glass professional can explain the repair options, but only your insurer can confirm coverage and claim consequences.
3. Take clear photos and record the details
Before a repair or replacement, take several photos in good light. Capture the damage from outside the vehicle, from inside the cabin, and from a few feet back to show its location on the windshield. If a stone or road hazard caused the damage, note the date, approximate time, location, and what happened.
Keep your policy number, vehicle identification number, license plate, and insurer contact information nearby. These details make the conversation faster whether you call the insurer yourself or authorize a glass provider to assist with the claim process.
There is no need to overcomplicate the description. “A rock from highway traffic hit the passenger-side windshield and the chip developed into a six-inch crack” is more useful than trying to diagnose the glass yourself.
4. Get an honest repair-versus-replacement assessment
A windshield repair is usually the least disruptive option when the damage is small, outside the driver’s primary viewing area, and has not contaminated the glass with moisture or dirt. During repair, a technician injects resin into the damaged area, then cures and polishes it to restore strength and reduce the visible mark.
Repair is not always appropriate. Replacement is generally the safer recommendation when there are multiple cracks, deep impact damage, edge cracks, damage in the driver’s critical viewing zone, or signs that the inner glass layer has been affected. Modern windshields are laminated safety glass, not just a clear barrier against wind and rain. They are a structural component of the vehicle.
Ask the technician to explain why they recommend repair or replacement. A clear answer should address the damage location, depth, size, and your vehicle’s safety systems. The goal is not to sell more glass. It is to restore safe visibility and road-ready protection.
5. Start the windshield insurance claim in Ontario
When you contact your insurer, explain that you need to report windshield damage and ask what documentation they need. They may provide a claim number, confirm your deductible, and explain whether an estimate or inspection is required. Write down the representative’s name, the claim number, and any authorization instructions.
Many auto-glass shops work with major Ontario insurers and can help verify coverage information or submit the required paperwork after you authorize them to do so. That can save time, but you should still understand what is being billed, what insurance has approved, and what amount you are responsible for paying.
Be cautious of anyone who promises that a claim will cost you nothing before reviewing your policy. Transparent service means discussing the deductible, glass options, calibration needs, taxes, and any non-covered work before the job begins.
6. Do not overlook ADAS calibration
If your windshield has a forward-facing camera, lane-departure warning, automatic emergency braking, adaptive cruise control, traffic-sign recognition, or similar technology, replacement may require ADAS calibration. These systems depend on precise camera positioning and accurate sensor alignment.
A windshield can look perfectly installed while a camera is slightly out of specification. That is why calibration is a safety-critical step, not an optional add-on. Depending on the vehicle, the procedure may be static, dynamic, or both. Static calibration is performed with specialized targets in a controlled setup. Dynamic calibration requires a road procedure under specific driving conditions.
Ask whether your vehicle requires calibration, how it will be completed, and whether the work will be documented. OEM-standard glass installation and proper ADAS calibration protect more than appearance – they help ensure the driver-assistance features respond as designed.
7. Choose workmanship, not just the fastest appointment
Same-day service is valuable when a windshield is cracked, but speed should not come at the expense of fit, bonding, or calibration. A proper replacement involves preparing the pinch weld, using the correct urethane adhesive, installing compatible glass, allowing appropriate safe-drive-away time, and checking the finished work carefully.
You should also receive clear aftercare instructions. For example, avoid slamming doors immediately after installation, leave retention tape in place if used, and follow the technician’s guidance about washing the vehicle or driving before the adhesive has fully cured. These small steps protect the bond that keeps the windshield securely in place.
For GTA drivers who cannot lose a workday, mobile service can be a practical option when conditions allow. Xtreme Auto Glass provides certified, insured technicians who can assess the damage, complete qualified repairs or replacements, and address calibration requirements with precision and care.
A claim should never distract from the reason the windshield matters in the first place: you need a clear view of the road and glass that can protect you when conditions turn unpredictable. Start with an honest assessment, ask direct questions about your coverage, and choose a repair partner that treats your vehicle’s safety systems with the care they deserve.
4 Responses